6 Best Long-Term Care Insurance Planners for Decades of Peace of Mind
Explore 6 top compact planners for long-term care insurance. These essential tools help you navigate complex policies and secure your future well-being.
Imagine a water pipe bursts in your home while you’re on a two-week cruise. Your house-sitter needs the insurance policy number, the plumber’s contact, and the location of the water main shutoff, but the information is scattered across three different drawers. A well-organized planner turns this potential catastrophe into a manageable inconvenience, and the same principle applies to your long-term care strategy. This isn’t about planning for a crisis; it’s about designing a system for clarity and control, ensuring your wishes are known and your affairs are in order for decades to come.
|
|
|
|
$28.99
|
|
$17.99
|
Friendly Disclaimer : This content is for educational & general research purposes only. Please consult healthcare providers or other qualified professionals for personalized medical, caregiving, or health-related advice.
Disclosure: As an Amazon Associate, this site earns from qualifying purchases. Thank you!
Why a Planner is Key for Your LTC Strategy
A long-term care strategy is more than just an insurance policy. It’s a comprehensive ecosystem of legal documents, financial accounts, medical information, and personal preferences that will guide your future. Without a central hub, this critical information often ends up fragmented—a will in a safe deposit box, a power of attorney with your lawyer, and insurance paperwork in a filing cabinet. This disorganization creates a stressful scavenger hunt for you or your loved ones when the information is needed most.
A dedicated planner acts as the master key to your entire life administration. It doesn’t necessarily hold the original documents, but it provides a clear, concise roadmap to where everything is and who to contact. Think of it as the table of contents for your life’s essential paperwork. This simple act of organization is one of the most powerful steps you can take to protect your autonomy and reduce the burden on your family.
When you need to activate a long-term care policy or when a designated power of attorney needs to step in, clarity is paramount. A well-maintained planner eliminates ambiguity and guesswork. It ensures that the people you’ve entrusted with your care have the immediate information they need to act confidently and in accordance with your wishes, preserving the independence you’ve worked so hard to build.
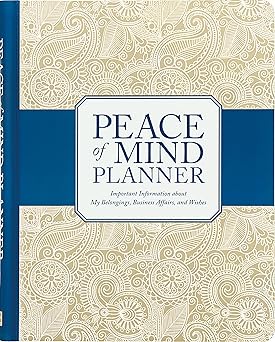
Smead Peace of Mind Planner for Easy Filing
For those who appreciate the tangible nature of a well-organized filing cabinet, the Smead Peace of Mind Planner is an excellent system. It’s less of a bound book and more of a structured kit designed to integrate directly with your existing physical files. It provides the framework to sort, label, and locate every crucial piece of paper, from birth certificates to property deeds.
This planner is built around a system of guided checklists and pre-labeled folders. It prompts you to gather specific documents and gives you a designated place for them, transforming a daunting pile of paperwork into a logical, accessible archive. Its strength lies in its procedural nature; it guides you through the process of organization, ensuring no critical document is overlooked.
The primary benefit here is the direct link between the plan and the physical documents. When your planner indicates where your will is, it’s not an abstract location but a specific, labeled folder within the same system. This approach is ideal for individuals who want a single, secure, and self-contained location for their most important physical records.
Kunida’s "I’m Dead, Now What?" for Full Prep
The title is blunt, but its purpose is profoundly considerate. This planner tackles the uncomfortable questions head-on, creating a comprehensive guide for the people you leave behind. Its scope extends far beyond typical financial and legal matters, venturing into the practical and personal details that often cause the most stress for grieving families.
"I’m Dead, Now What?" is designed to be an exhaustive instruction manual for your life. It includes sections for:
- Digital Life: Passwords for email, social media, and online accounts.
- Household Operations: Instructions for pet care, contacts for service providers, and locations of spare keys.
- Personal Wishes: Detailed preferences for funeral arrangements and the handling of personal effects.
- Key Contacts: A full list of your lawyers, accountants, doctors, and friends.
By completing this planner, you are giving your loved ones a remarkable gift: the freedom to focus on their grief rather than a frantic search for information. It anticipates their questions and provides clear answers, preventing small logistical hurdles from becoming major emotional burdens. This planner is for the pragmatist who wants to ensure a smooth transition and leave behind a legacy of order and care.
The Personal Affairs System for Legal Documents
When your primary concern is the meticulous organization of legal and financial instruments, The Personal Affairs System offers a focused, no-frills solution. This system is structured like a professional portfolio, designed specifically to house and index the documents that form the backbone of any estate plan. It prioritizes clarity and function for the individuals who will eventually need to execute your affairs.
This planner is essentially a purpose-built binder with dedicated sections for wills, trusts, power of attorney documents, insurance policies, and investment account statements. Its design facilitates a straightforward review by an executor, trustee, or financial advisor. The emphasis is on creating an official, easy-to-navigate record that streamlines the legal and administrative processes that follow a major life event or death.
While it may be less personal than other planners, its strength is its professional utility. It ensures that when your designated agent needs to locate a specific stock certificate or the details of a life insurance policy, the information is precisely where it should be. This system is an excellent choice for those with complex estates or anyone who wants to provide their executor with a tool that speaks their language.
NOLO’s "Get It Together" for Estate Planning
NOLO has built a reputation for making complex legal topics accessible, and "Get It Together" is a prime example of that mission. This product is more than just a planner; it’s an educational tool that guides you through the why behind the documents you’re organizing. It empowers you to not only collect your information but also to understand its significance in your broader estate and long-term care plan.
The planner is structured to teach as it organizes. Each section provides context and explains the purpose of the information you’re recording, from creating a net worth statement to understanding the role of a healthcare directive. This approach helps you identify gaps in your planning and facilitates more productive conversations with your attorney, financial planner, and family members. You’re not just filling in blanks; you’re actively engaging with your own strategy.
"Get It Together" is ideal for the proactive individual who wants to be a knowledgeable participant in their own planning process. By using this tool, you build a comprehensive record while also increasing your own literacy in estate and elder law. The result is a well-organized life and the confidence that comes from making informed, deliberate decisions about your future.
Erin Condren Emergency Binder for Quick Access

A plan is only useful if it’s easy to use, especially in a hurry. The Erin Condren Emergency Binder leverages smart, intuitive design to make critical information accessible at a glance. For those motivated by clean aesthetics and a user-friendly interface, this binder turns the often-intimidating task of organization into a more approachable and even pleasant experience.
This binder focuses on the essentials needed in an urgent situation. With clear, colorful tabs and logically organized sections, it prompts you for the most vital information:
- Medical Details: Allergies, medications, doctor contacts, and insurance information.
- Household Contacts: Key numbers for utilities, plumbers, and electricians.
- Family Information: Contact details and essential information for each family member.
While it may not be as exhaustive as a dedicated estate planning system, its strength is its immediacy. This is the binder you grab in an emergency. It provides a quick-reference guide for a family member or first responder, ensuring they have the critical data needed to make fast, informed decisions without having to sort through dense legal or financial paperwork.
The Evergreen Planner: A Gentle Family Guide
Planning for the future involves more than just finances and legalities; it’s also about communicating your values, wishes, and life story. The Evergreen Planner is designed as a tool for connection, gently guiding you to document the personal and sentimental details that are often the most meaningful to family. It frames end-of-life planning not as a morbid task, but as an act of love and legacy.
This planner uses thoughtful prompts to help you share your personal history, wisdom, and preferences in a non-threatening way. It encourages you to write down favorite memories, explain the significance of certain heirlooms, and articulate your hopes for your loved ones. It also provides a structured, gentle way to state your wishes for medical care and final arrangements, ensuring your values are understood and respected.
The true value of The Evergreen Planner lies in its ability to facilitate conversations and preserve the person behind the paperwork. It serves as a bridge between generations, capturing your voice and essence for your family to cherish. For those who want their long-term care and estate plan to reflect their whole self, this planner offers a beautiful and holistic approach.
Choosing Your Planner: Digital vs. Physical
Ultimately, the best planner is the one you will consistently use and maintain. The choice between a physical binder and a digital system is deeply personal, and each has distinct advantages and tradeoffs. Your lifestyle, comfort with technology, and how you envision the information being accessed should guide your decision.
A physical planner offers tangible simplicity. It requires no password, is immune to cyber threats, and can be easily accessed by a loved one in your home without technical assistance. However, it is vulnerable to physical damage from fire or water and can only exist in one place at a time. A secure, fireproof safe is essential for protecting these vital original documents and records.
A digital system, whether a specialized app or a secure cloud folder, offers unparalleled convenience. It can be updated instantly, accessed from anywhere, and securely shared with trusted individuals in different locations. The primary drawbacks are the reliance on technology—passwords can be forgotten, and access can be lost during a power outage—and the persistent risk of data breaches.
For many, a hybrid approach offers the best of both worlds. Use a digital platform for easy updates and for sharing information with family and professional advisors. Then, print a master copy of the most critical information annually and store it in a fireproof safe at home or in a bank’s safe deposit box. This ensures both convenient accessibility and a resilient, tangible backup when you need it most.
Taking the time to organize your affairs is a profound act of self-reliance and a gift to those you love. By choosing a system that fits your style and thoughtfully completing it, you are not just preparing for the future; you are actively designing it. This simple, powerful step ensures your legacy is one of clarity, control, and peace of mind.
Frequently Asked Questions (FAQs)
What does a long-term care insurance planner do?
A long-term care insurance planner evaluates your health history, retirement assets, and family needs to design and broker an appropriate extended-care policy. These specialists assess whether traditional, asset-based, or life insurance hybrid coverage fits your budget. They also guide you through medical underwriting, quote multiple carriers like Mutual of Omaha or Lincoln Financial, and help manage rate increase risks over your lifetime.
What is a fee-only long-term care insurance planner?
Fee-only long-term care insurance planners are advisors who charge an hourly rate or flat consulting fee instead of taking insurance carrier commissions. Because these advisors do not profit from policy sales, they provide unbiased reviews of existing coverage or advise when self-funding is safer. Typical flat fees range between $500 and $2,500, depending on the complexity of your estate.
How do I choose a long-term care insurance planner for aging parents?
Choose a planner for aging parents by verifying their credentials, such as the Certified Long-Term Care (CLTC) designation, and confirming they represent multiple top-rated insurers. Ask how many carriers they quote and whether they specialize in medical underwriting for applicants in their 60s or 70s. Review carrier financial strength ratings through AM Best, aiming for A or better, to ensure future claims will be paid promptly.
How long does it take to get approved for long-term care insurance through a planner?
Approval for long-term care insurance generally takes four to eight weeks from the date your planner submits the completed medical application. The underwriting timeline depends on how quickly your physicians provide electronic medical records and whether the insurer requires a telephone interview or in-person cognitive assessment. Working with a specialist who pre-screens your health records can prevent underwriting delays.
Which is better, an independent broker or a captive long-term care insurance agent?
Independent brokers are typically better for long-term care insurance because they compare plans across multiple insurers rather than selling products from a single company. A captive agent can only offer policies from their employer, which limits your choices if you have pre-existing health conditions. Independent brokers shop around with carriers like Nationwide, Securian, or OneAmerica to find the lowest premium for your specific medical profile.
How much does it cost to use a long-term care insurance planner?
Working with a commissioned long-term care insurance planner costs you nothing directly because the insurance company pays the agent’s commission out of the policy premium. Premium rates are legally mandated and filed with state insurance departments, meaning your policy costs the exact same amount whether you use a planner or buy directly. If you choose an independent fee-only consultant instead, expect an hourly rate between $200 and $450.
What is the biggest mistake people make when hiring a long-term care insurance planner?
Waiting until health issues arise before consulting a long-term care insurance planner is the costliest mistake consumers make. Underwriting guidelines are strict, and pre-existing conditions like diabetes complications or memory loss can trigger immediate denials. Consulting a planner in your mid-50s secures lower baseline rates, preserves good-health discounts, and avoids the 50% to 100% price surcharges common in later years.
Is long-term care insurance worth buying if you are already over age 65?
Long-term care insurance can still be worth buying after age 65 if you are in good health and want to protect substantial retirement savings from nursing care costs. Annual premiums increase dramatically past 65, often exceeding $4,000 to $7,000 per year for comprehensive coverage. For many older applicants, hybrid life and long-term care policies work better than traditional policies because unspent benefits transfer to heirs upon death.

