6 Easy Tax Guides for Senior Medical Deductions That Maximize Returns
Seniors can maximize tax returns by deducting medical costs. This guide simplifies AGI thresholds and lists qualified expenses to help you save more.
Making smart financial moves is just as important as choosing the right grab bar or lighting fixture for your home. Many of the expenses that support your health and independence as you age can significantly lower your tax bill, but the rules can feel complex. Understanding these deductions allows you to invest in your well-being with more confidence, turning necessary costs into strategic financial advantages.

Friendly Disclaimer : This content is for educational & general research purposes only. Please consult healthcare providers or other qualified professionals for personalized medical, caregiving, or health-related advice.
Disclosure: As an Amazon Associate, this site earns from qualifying purchases. Thank you!
Understanding the 7.5% AGI Deduction Threshold
Before any medical deduction can be claimed, you must first clear a specific hurdle set by the IRS. You can only deduct the amount of your total medical expenses that exceeds 7.5% of your Adjusted Gross Income (AGI). Think of your AGI as your gross income minus certain adjustments, a figure you’ll find on your tax return.
Let’s use a simple example. If your AGI for the year is $80,000, the 7.5% threshold is $6,000. This means you need to have more than $6,000 in qualified medical expenses before you can deduct a single dollar. If your total medical costs are $9,500, you would subtract the $6,000 threshold and could potentially deduct $3,500.
This threshold is precisely why meticulous tracking of every potential expense is so critical. A prescription co-pay here and a specialist visit there might seem small, but they accumulate. When combined with larger costs like dental work or a significant home modification, you may find you easily surpass the 7.5% AGI floor, unlocking valuable tax savings.
Tax Rules for Your Kohler Walk-In Tub Purchase
Enjoy a therapeutic bathing experience with the ANZZI Walk-In Tub, featuring whirlpool and air jets for a full-body massage. It includes a quick-fill faucet with a handheld shower, aromatherapy, chromatherapy, and safety features like a low-entry threshold and grab bars.

A common question is whether a major home improvement, like installing a walk-in tub, qualifies as a medical deduction. The answer is yes, but with an important condition: the primary reason for the purchase must be medical care. A doctor’s recommendation documenting the need for hydrotherapy for arthritis or for safer bathing due to a mobility concern provides strong support for the deduction.
However, the IRS views this type of project as a "capital improvement," which has a specific calculation. You can deduct the cost of the purchase and installation minus any increase in your home’s value as a result of the improvement. For instance, if the walk-in tub costs $17,000 to install but an appraiser determines it only increases your home’s market value by $6,000, your potential medical deduction is the difference: $11,000.
In some cases, a modification may not increase your home’s value at all. Widening doorways or installing an entrance ramp, for example, might be deemed to have no impact on the resale price. In that scenario, the entire cost of the project could be included in your medical expense calculations. This is where professional advice from both a contractor and a tax advisor becomes invaluable.

Is Your Drive Medical Nitro Rollator Deductible?

Equipment that assists with mobility and daily living falls under the category of Durable Medical Equipment (DME), and its cost is often deductible. Items like a rollator, walker, cane, hospital bed, or wheelchair are considered medical expenses when they are necessary to alleviate a physical condition. The key is that the equipment must be used to diagnose, treat, mitigate, or prevent a disease.
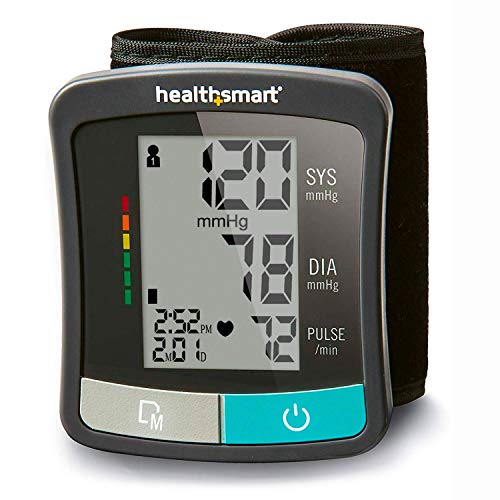
For an item to qualify, it typically needs to be medically necessary. While you might purchase a rollator for convenience, its cost becomes a clear medical expense when a doctor or physical therapist prescribes it to improve stability, prevent falls, or manage a chronic condition like COPD or severe arthritis. Keep the prescription or doctor’s letter with your tax records as proof of medical necessity.
Documenting In-Home Care and Nursing Services
As needs evolve, you may plan for in-home support. The deductibility of these services depends entirely on the nature of the care provided. The costs of a licensed nurse performing medical tasks—such as administering medication, changing dressings, or providing injections—are fully deductible as medical expenses.
The rules get more nuanced when care blends medical and personal tasks. If a caregiver provides personal services like bathing, grooming, or meal preparation, those costs are generally not deductible. However, if these personal services are incidental to and provided by a licensed nurse as part of a broader medical care plan, the entire cost may be deductible. For example, if a nurse spends their time primarily on medical duties but also assists with bathing, the full payment for their services can be included.
Clear documentation is non-negotiable. Keep detailed invoices and a log that separates services:
- Medical Services: Note tasks performed by a licensed professional (RN, LPN, etc.).
- Personal Care: Note tasks like housekeeping, cooking, and companionship. This record-keeping will be essential for you or your tax professional to accurately determine the deductible portion of your in-home care costs.
Calculating Mileage for Medical Appointments
The miles you drive for medical care can add up to a significant deduction that is frequently overlooked. This includes travel to see a doctor, dentist, physical therapist, or chiropractor. It also covers trips to the pharmacy to pick up prescriptions.
To claim this deduction, you must keep a contemporaneous log of your travel. A simple notebook in your car or a mileage-tracking app on your phone works perfectly. For each trip, record the:
- Date of travel
- Name and address of the medical provider or pharmacy
- Total round-trip mileage
The IRS sets a standard medical mileage rate each year (for example, it was 22 cents per mile for the 2023 tax year). You simply multiply your total medical miles by this rate to find your deduction. Don’t forget that you can also include the cost of parking fees and tolls, so keep those receipts.
Deducting Long-Term Care Insurance Premiums
If you’ve proactively planned for future needs with a long-term care (LTC) insurance policy, a portion of your premiums may be tax-deductible. The policy must be "tax-qualified," meaning it meets federal standards for consumer protection and benefits. Most policies sold today meet this requirement, but it’s wise to confirm with your insurance provider.
The amount you can deduct is capped based on your age at the end of the tax year. The IRS adjusts these limits periodically for inflation. While you should always consult the current year’s official figures, the age-based limits for a recent tax year looked like this:
- Age 40 or under: Limit on deduction
- Age 41 to 50: Higher limit
- Age 51 to 60: Even higher limit
- Age 61 to 70: A substantial limit
- Age 71 or over: The highest limit
These premiums are bundled with all your other medical expenses. They are not a separate deduction but are added to your total, which must then exceed the 7.5% AGI threshold to provide a tax benefit.
Tracking Prescription and Over-the-Counter Costs
The cost of prescription medications, including insulin, is a fully deductible medical expense. For most people, the easiest way to track this is to ask your pharmacy for a year-end printout of your expenses. This document provides a clean, accurate total and saves you from having to collect dozens of individual receipts.
Thanks to legislative changes, you can once again deduct the cost of many over-the-counter (OTC) products without a doctor’s prescription. This includes items like pain relievers, allergy medications, first-aid supplies, and cold remedies. This change makes it easier to include these everyday health-related purchases in your total medical expense calculation.
Create a simple system to track these costs. Keep a dedicated envelope or folder for receipts from drugstores and supermarkets. At the end of the year, go through them with a highlighter to tally up the qualified OTC expenses. It’s a small habit that can make a surprising difference when you’re working to meet that 7.5% AGI threshold.
Using IRS Publication 502 for Your Tax Return
When you have a specific question about whether an expense is deductible, the definitive guide is IRS Publication 502, "Medical and Dental Expenses." This document provides a comprehensive A-to-Z list of what you can and cannot include in your medical expense calculations. It is written in relatively plain language and is the source of truth for these rules.
You don’t need to read it cover-to-cover. Instead, think of it as your personal reference library. If you’re wondering whether you can deduct the cost of an air purifier or special dietary foods, you can look it up directly in Publication 502. Being an informed taxpayer empowers you to have more productive conversations with your financial advisor or tax preparer, ensuring no valid deduction is missed.
Taking control of your medical deductions is an empowering part of managing your financial health for the long term. By understanding the rules and keeping organized records, you can reduce your tax burden and make your investments in safety and wellness work even harder for you. This proactive approach ensures you are well-positioned to live independently and comfortably, on your own terms.
Frequently Asked Questions (FAQs)
What is the 7.5 percent adjusted gross income rule for senior medical deductions?
The IRS 7.5 percent rule allows taxpayers to deduct only the portion of unreimbursed qualified senior medical expenses that exceeds 7.5 percent of their adjusted gross income. For example, if a senior reports an adjusted gross income of $40,000, the first $3,000 of medical expenses is not deductible. If that senior pays $5,500 in eligible healthcare bills during the calendar year, they can deduct the remaining $2,500 on Schedule A.
What qualifies as an eligible expense for senior medical deductions?
Qualified senior medical deductions include unreimbursed payments for prescription medications, doctor visits, hospital stays, dental treatments, eyeglasses, hearing aids, and durable medical equipment. Seniors can also include Medicare Part B and Part D premiums, along with transportation costs like ambulance fees or mileage to medical appointments. Non-prescription supplements, elective cosmetic procedures, and general gym memberships are strictly non-deductible under IRS Publication 502 guidelines.
How do I claim senior medical deductions on Schedule A?
Seniors claim medical deductions by itemizing qualified out-of-pocket health expenses on IRS Form 1040, Schedule A, rather than taking the standard deduction. Gather receipts, bank statements, and year-end summaries to calculate total unreimbursed payments on line 1 of Schedule A. Next, enter adjusted gross income on line 2, multiply it by 7.5 percent on line 3, and subtract that figure from total costs on line 4 to determine the final deduction.
How do self-employed seniors deduct Medicare premiums on taxes?
Self-employed seniors deduct Medicare premiums as an above-the-line adjustment directly on Schedule 1 of Form 1040 without needing to itemize deductions. Enter eligible payments for Medicare Parts B, D, and Medicare Advantage plans on line 17 of Schedule 1. The total deduction cannot exceed net profit from self-employment, and you cannot claim this deduction if you or your spouse were eligible for an employer-subsidized health plan during that month.
Is the standard deduction or itemizing senior medical deductions better for retirees?
Choosing between the standard deduction and itemizing senior medical deductions depends on whether total itemized write-offs exceed the enhanced senior standard deduction amount. Taxpayers age 65 and older receive an extra standard deduction allowance added to their base deduction. If total deductible medical expenses, state taxes, and charitable gifts combined are less than this heightened standard threshold, taking the standard deduction yields a larger tax benefit.
How much can seniors deduct for long-term care insurance premiums?
Age-based limits restrict how much long-term care insurance premium costs seniors can include in their medical expense deductions each tax year. For the 2024 tax year, individuals aged 61 to 70 can deduct up to $4,710 in qualified premiums per person, while those older than 70 can deduct up to $5,880. These amounts count toward the general medical expense total subject to the 7.5 percent adjusted gross income limitation.
What common mistakes cause seniors to lose their medical expense deductions?
Deducting costs covered by insurance or paid through tax-free health accounts is the most frequent error seniors make with medical deductions. You can only deduct out-of-pocket medical bills that you personally paid and were never reimbursed for by Medicare, supplemental plans, or Health Savings Accounts. Keep detailed Explanation of Benefits statements alongside receipts to prove that insurance did not cover the claimed expenses if the IRS requests documentation.
Is it worth tracking medical expenses for senior tax deductions if income is low?
Tracking senior medical deductions is worthwhile when lower annual taxable income or catastrophic healthcare costs push total itemized deductions above the standard deduction threshold. Because the 7.5 percent floor is tied to adjusted gross income, a lower retirement income actually makes it easier to surpass the hurdle. Seniors facing assisted living fees, extensive dental surgery, or private nursing care often save thousands of dollars by maintaining meticulous records and itemizing.