Best Medicare Part D Plans for Arthritis Medication
The right Part D plan can lower arthritis drug costs. We analyzed 6 top plans many overlook, focusing on formularies and savings for key medications.
Managing the daily realities of arthritis is a key part of maintaining an active, independent life. While you may have a handle on your physical routine, the unpredictable cost of medication can quickly disrupt your financial stability. Choosing the right Medicare Part D plan isn’t just about saving money; it’s a strategic move to ensure you have consistent, affordable access to the treatments that keep you moving.

Friendly Disclaimer : This content is for educational & general research purposes only. Please consult healthcare providers or other qualified professionals for personalized medical, caregiving, or health-related advice.
Disclosure: As an Amazon Associate, this site earns from qualifying purchases. Thank you!
Understanding Part D for Chronic Arthritis Pain
Living with arthritis often means relying on a consistent medication regimen, which can range from over-the-counter anti-inflammatories to complex biologic drugs. This is where Medicare Part D becomes a critical planning tool. The challenge is that not all plans view arthritis medications equally, and the one with the lowest monthly premium might leave you with staggering costs at the pharmacy counter.
The key is to look past the premium and understand a plan’s formulary—its official list of covered drugs. Medications on this list are sorted into tiers, with Tier 1 typically being preferred generics with the lowest copay, and higher tiers (like Tier 5) reserved for specialty brand-name drugs with the highest costs. For arthritis, a simple generic like methotrexate might be Tier 1, while a biologic like Humira could be a Tier 5 specialty drug, with thousands of dollars difference in annual cost.
Therefore, your primary task is to find a plan whose formulary aligns with the specific medications you take. A plan that places your essential brand-name drug in a lower tier, or has a robust selection of generic anti-inflammatories, can be the difference between a manageable budget and a major financial burden. This proactive check is one of the most powerful steps you can take to protect your long-term independence.
Aetna SilverScript: Broad Arthritis Drug Coverage
Many people managing a chronic condition find their medication needs can change over time. A drug that works today might be less effective next year, requiring a switch. This is where Aetna’s SilverScript plans often shine, as they are frequently designed with broad and comprehensive formularies.
A broad formulary increases the likelihood that both your current and potential future arthritis medications are covered. This provides a valuable safety net, reducing the stress of wondering whether a new prescription from your rheumatologist will be covered. SilverScript typically offers several plan levels, such as a basic "SmartRx" and a more comprehensive "Plus" option.
This tiered approach allows you to balance your monthly premium against the potential out-of-pocket costs. If you primarily use generics, the lower-premium plan may be sufficient. However, if you rely on or anticipate needing brand-name or specialty drugs, the higher-premium plan might offer better cost-sharing on those expensive medications, making it the more economical choice over the course of a year.
Humana Walmart Value Rx: Low Copay Arthritis Meds
For those whose arthritis is well-managed with common generic medications, the Humana Walmart Value Rx plan can be an incredibly cost-effective option. This plan is often structured to offer very low, sometimes even $0, copays for preferred generic drugs filled at preferred pharmacies like Walmart. This can dramatically lower your monthly medication expenses.
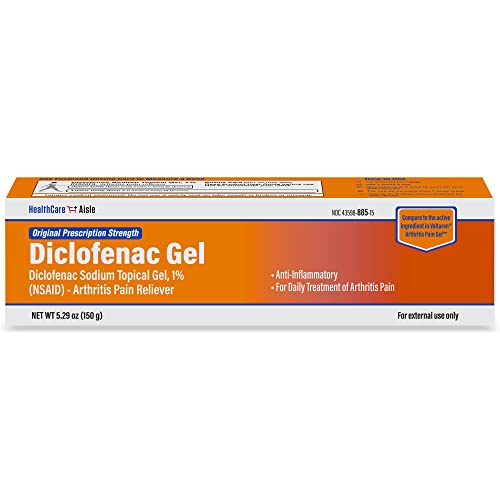
The plan’s appeal is its straightforward value proposition: a low monthly premium combined with predictable, minimal costs for the most common prescriptions. If your doctor has you on generic NSAIDs (like diclofenac) or DMARDs (like sulfasalazine), you could see significant savings. This strategy frees up funds in your monthly budget for other wellness activities that support your independence.
The important tradeoff to consider is the network. While costs are low at preferred pharmacies, they can be substantially higher at non-preferred locations. Furthermore, the formulary may be more restrictive when it comes to brand-name or specialty drugs. It’s an excellent fit for a specific need but requires you to confirm your exact medications and pharmacy habits align with the plan’s structure.
Wellcare Value Script: Tier 1 Arthritis Generics
When your top priority is keeping fixed monthly costs as low as possible, the Wellcare Value Script plan often emerges as a leading contender. It consistently features one of the lowest monthly premiums on the market in many regions. This makes it an attractive starting point for anyone building a lean, predictable retirement budget.
The strength of this plan lies in its coverage of Tier 1 generic drugs. For individuals managing osteoarthritis or rheumatoid arthritis with long-established, common generic medications, the savings can be substantial. The plan is designed for high-volume, low-cost prescriptions, making routine refills simple and affordable.
However, this low-premium model means you must be diligent in checking the formulary for your specific needs. If you require even one brand-name medication, its cost on a plan like this could quickly erase any savings from the low premium. This plan is a powerful tool for the right person, but it’s essential to verify that its lean formulary fully supports your treatment plan.
Cigna Secure Rx for Convenient Mail-Order Refills
Managing a chronic condition is about creating sustainable, convenient routines. For many, trekking to the pharmacy each month is a needless chore. Cigna’s plans, like the Secure Rx, often stand out for their efficient and cost-effective mail-order pharmacy benefits, a feature that directly supports an independent lifestyle.
Receiving a 90-day supply of your maintenance arthritis medication by mail simplifies your life. It reduces trips out, ensures you have your medication on hand, and can often come with a lower copay than three separate 30-day refills from a retail pharmacy. This is a practical benefit that gives you back time and energy.
When evaluating a Cigna plan, pay close attention to the preferred mail-order pricing. For someone on a steady, long-term regimen of one or more arthritis drugs, these savings can add up significantly over a year. It transforms medication management from a recurring task into a simple, automated part of your wellness plan.
AARP MedicareRx by UHC: Member Savings on Meds
For many, there’s comfort and reliability in choosing a plan from a large, established carrier. The AARP MedicareRx plans, administered by UnitedHealthcare (UHC), are among the most popular and widely recognized Part D options. Their significant market presence often translates into a vast network of preferred pharmacies.
This large network is a key feature for active adults who travel or split their time between different locations. With an AARP/UHC plan, you are more likely to find an in-network pharmacy with preferred pricing wherever you are. Plans often feature low copays on many common generics, particularly at preferred retailers like Walgreens, providing both savings and convenience.
Because UHC is such a large player, their formularies are often very robust, covering a wide array of medications used to treat various forms of arthritis. While their premiums may not always be the absolute lowest, the combination of a strong formulary, a huge pharmacy network, and member-focused savings programs makes them a dependable choice for long-term planning.
Mutual of Omaha Rx: Predictable Arthritis Costs

Budgeting in retirement is about creating predictability. Mutual of Omaha Rx plans are often designed with this principle in mind, offering clear, straightforward cost structures that help you anticipate your out-of-pocket expenses for arthritis medications.
These plans frequently provide predictable copays for generic and preferred brand-name drugs, especially during the initial coverage stage before you meet your deductible. This clarity helps you plan your annual healthcare spending with greater confidence, avoiding the sticker shock that can come with more complex plan designs. They aim to provide a stable, easy-to-understand benefit.
While they may not always have the lowest premium or the widest formulary, their value lies in financial predictability. For someone who prioritizes a stable, no-surprises budget for their chronic condition management, a Mutual of Omaha Rx plan is a compelling option worth careful consideration. It’s a plan built for planners.
Choosing Your Plan: Match Meds to the Formulary
The names and specific benefits of these plans can change annually, but the method for choosing the right one remains the same. The "best" plan is not a brand name; it is the one that costs you the least amount of money over the entire year for the specific drugs you take.
Your first and most important step is to create a precise list of your medications.
- Drug Name: Write down the exact spelling (e.g., Celecoxib, not just "arthritis pill").
- Dosage: Note the strength (e.g., 200 mg).
- Frequency: Record how often you take it (e.g., once daily).
With this list in hand, use the official Medicare Plan Finder tool at Medicare.gov. This government website allows you to enter your medications and compare every plan available in your zip code. It calculates your estimated total annual cost—including premiums, deductibles, and copays—for each one. Look past the premium and focus on that total cost. A plan with a $50 premium might save you a thousand dollars over a year compared to a $15 premium plan if it covers your key medication more favorably. This simple act of matching your personal pharmacy needs to a plan’s formulary is the single most effective way to control your medication costs and support your long-term health and independence.
Ultimately, selecting a Part D plan is an exercise in foresight and control, much like modifying your home for the future. By investing a little time to research and match a plan to your specific health needs, you are actively designing a more secure and independent life. This proactive decision empowers you to focus on living well, not on worrying about the next pharmacy bill.
Frequently Asked Questions (FAQs)
What is a Medicare Part D formulary tier for arthritis medication?
A Medicare Part D formulary tier is a drug pricing category that determines your out-of-pocket copay or coinsurance for specific arthritis medication. Plans usually group arthritis drugs into five tiers, placing generic pain relievers on Tiers 1 and 2, brand-name options on Tier 3, and expensive biologic injections on Tier 4 or 5. Higher tiers require a percentage-based coinsurance, often between 25% and 33%, rather than a fixed flat copayment. Check your plan’s formulary document to confirm which tier your drug falls into.
What does step therapy mean on a Medicare Part D plan for arthritis?
Step therapy is a utilization management rule requiring you to try lower-cost arthritis medications before your Medicare Part D plan approves a costlier prescribed alternative. For example, your insurer may require you to take generic methotrexate before approving a biologic like Humira or Enbrel. If the initial drug causes adverse reactions or fails to relieve symptoms, your rheumatologist can submit clinical documentation to request a step therapy override.
How do I compare Medicare Part D plans for arthritis medication on Medicare.gov?
You compare Medicare Part D plans by entering your exact arthritis prescriptions, dosages, and preferred pharmacies into the official Medicare Plan Finder tool on Medicare.gov. The tool sorts available policies by lowest total drug and premium cost rather than monthly premium alone. Review each plan’s restrictions, such as prior authorization or quantity limits, before enrolling. You can complete this comparison and enroll during the Annual Enrollment Period from October 15 through December 7.
How do I request a formulary exception for non-covered arthritis drugs under Medicare Part D?
Your prescribing doctor must submit a formal coverage determination request and supporting statement to your Medicare Part D insurer to request a formulary exception. The doctor must certify that formulary alternatives are clinically ineffective or would cause severe adverse effects. Insurers must provide an answer within 72 hours for standard reviews, or within 24 hours for expedited requests when waiting poses serious health risks.
Which is better for rheumatoid arthritis medication, Medicare Advantage or standalone Part D?
Standalone Medicare Part D plans paired with Original Medicare and a Medigap policy typically offer greater provider flexibility and fewer network barriers for complex rheumatoid arthritis treatments. Medicare Advantage plans combine drug and medical benefits under one roof, often with low premiums, but they frequently mandate restrictive HMO provider networks and strict prior authorizations. If your arthritis requires specialized biologic infusions administered in an outpatient clinic, Medigap with standalone Part D generally minimizes administrative delays and out-of-pocket costs.
What is the maximum out-of-pocket cost for arthritis medication under Medicare Part D in 2025?
Out-of-pocket prescription drug costs under Medicare Part D are capped at $2,000 per calendar year starting in 2025. This annual limit applies to all covered formulary medications, protecting seniors taking expensive arthritis biologics from catastrophic expenses. Once your deductibles, copayments, and coinsurance reach $2,000, you pay $0 for your covered medications for the remainder of that calendar year. You can also opt into the Medicare Prescription Payment Plan to spread these payments across monthly installments.
Why did my Medicare Part D plan deny coverage for my arthritis medication?
Medicare Part D plans usually deny arthritis medication because the drug requires unmet prior authorization, is excluded from the formulary, or exceeds plan quantity limits. Insurers often require formal proof of medical necessity before paying for high-tier specialty drugs. If denied, inspect the written Notice of Denial from your plan, then ask your prescribing physician to file an immediate redetermination appeal with detailed clinical chart notes within 60 days.
Is Extra Help worth applying for to cover expensive arthritis medication on Medicare Part D?
Qualifying for the federal Extra Help program substantially lowers arthritis medication expenses by eliminating the Part D deductible and capping copays at minimal amounts. In 2024 and 2025, eligible individuals with limited income and assets pay no more than $4.50 to $4.90 for generics and $11.20 to $12.15 for brand-name drugs. Applying through the Social Security Administration can save thousands of dollars annually on specialty therapies if you meet the financial eligibility guidelines.


